401(k) Rollover Options in Red Bank & Monmouth County, NJ
Left a job or nearing retirement? Deciding what to do with an old 401(k) is one of the largest money moves you will make. As fee-based fiduciary CFP® professionals in Red Bank, we compare every option and the tax consequences of each, so you can move your retirement savings with confidence.
Understanding Your 401(k) Rollover Choices
When you leave an employer or approach retirement, the money in your 401(k) does not have to stay where it is. You generally have four paths: leave the funds in your former employer's plan, move them into a new employer's plan, roll them into an Individual Retirement Account (IRA), or cash out. Each path carries different tax treatment, investment options, fees, and long-term consequences.
A rollover is not automatically the right move, and cashing out early can trigger taxes and penalties that are hard to undo. The best choice depends on your plan's fees and investment menu, your age, your tax picture, and how you want to manage the account going forward. As an independent, fee-based fiduciary firm in Red Bank, Oceanic Capital Management helps families and business owners across Monmouth and Ocean County compare these options side by side and decide with a full understanding of the trade-offs.
Why Getting Your Rollover Right Matters
A rollover decision is one of the largest single money moves many people ever make. Small mistakes in timing or paperwork can cost thousands in avoidable tax, and some choices cannot be reversed. The federal rules below are worth understanding before you touch the account.
Is the additional federal tax that generally applies to the taxable portion of a 401(k) distribution taken before age 59½ and not rolled over, on top of ordinary income tax, unless an exception applies.1
The is the window to redeposit funds into another eligible retirement account in an indirect rollover. Miss it and the distribution is generally treated as taxable income.2
Mandatory federal withholding could cost your 20% on an eligible rollover distribution paid directly to you from an employer plan. You must replace that amount from other funds to roll the full balance over.2
If you separate from your employer in or after the year you turn 55, distributions from that employer's plan may avoid the 10% early-distribution tax. Rolling to an IRA first can forfeit this exception.3
A direct (trustee-to-trustee) rollover sidesteps the 60-day deadline and the 20% withholding trap entirely, which is why the IRS treats it as the simplest path. Knowing which route fits your age, tax bracket, and goals is where guidance pays for itself.
How We Help With Your 401(k)
Whether you are between jobs, newly retired, or simply want a second opinion on an old account, we walk through every option and the tax consequences of each before you commit.
Rolling Over To An IRA
Consolidate a former employer's 401(k) into an Individual Retirement Account for a wider range of investments and centralized management. We handle the direct rollover paperwork so funds move trustee to trustee, avoiding withholding and the 60-day deadline.
Explore IRA Planning ›Managing A 401(k) Without Rolling Over
Not ready to move the account? Through a collaboration with Pontera, we can provide professional oversight of your existing 401(k) while you keep contributing through your employer's plan, so the balance stays actively managed in the meantime.
In-Service Rollovers
Some plans permit rolling a portion of your 401(k) into an IRA while you are still employed. We review your plan document, confirm eligibility, and coordinate the transfer to give you more control without leaving your job.
Roth Conversion Analysis
A rollover can be the right moment to weigh converting pre-tax dollars to Roth. We model the tax impact across years so the decision fits your bracket and long-term plan.
Roth Conversion Strategies ›Retirement Income Planning
Your rollover is one piece of a larger picture. We coordinate Social Security timing, withdrawal sequencing, and healthcare costs into one plan.
Retirement Planning For Individuals ›Ongoing Investment Management
Once your funds are in place, we build and monitor a diversified, low-cost portfolio aligned with your goals, time horizon, and risk tolerance.
Investment Management ›Areas We Serve
Our home office is in Red Bank, New Jersey, and we help families and business owners with 401(k) rollovers and retirement planning throughout the region, including Middletown, Rumson, Fair Haven, Little Silver, Holmdel, Colts Neck, and the surrounding Monmouth and Ocean County communities.
Wherever you are along the Jersey Shore, we are nearby and ready to help, with in-person and virtual meetings available.
Areas We Serve
Our home office is in Red Bank, New Jersey, and we help families and business owners with 401(k) rollovers and retirement planning throughout the region, including Middletown, Rumson, Fair Haven, Little Silver, Holmdel, Colts Neck, and the surrounding Monmouth and Ocean County communities.
Wherever you are along the Jersey Shore, we are nearby and ready to help, with in-person and virtual meetings available.
Why Families Choose Us For Their Rollover
Choosing where to move your retirement savings comes down to trust. Our value is in experience, transparency, and a fiduciary standard of care that puts your interests first.
We are an independent Registered Investment Advisory firm rooted in Red Bank, New Jersey, so you get a direct relationship with the advisors managing your plan and face-to-face meetings when you want them.
-
✓
Fiduciary Standard Of Care
As an independent RIA, we are obligated to act in your best interest, with rollover recommendations driven by your goals, not product sales.
-
✓
50+ Years Combined Experience
Our managing directors have guided clients through bull and bear markets and countless job and life transitions.
-
✓
CFP® And CFA® Credentials
Both directors are CERTIFIED FINANCIAL PLANNER™ professionals, bringing rigorous training in tax, retirement, and investment planning.
-
✓
Rooted In Monmouth County
We live and work where our clients do, on Half Mile Road in Red Bank, serving families across Monmouth and Ocean County.
Douglas J Lyons, CFP®, CFA®, CDFA®
More than 30 years advising clients, formerly Executive Director of Private Wealth Consultants at UBS and part of Merrill Lynch's planning team. Holds the CFA®, CFP®, and CDFA® designations.
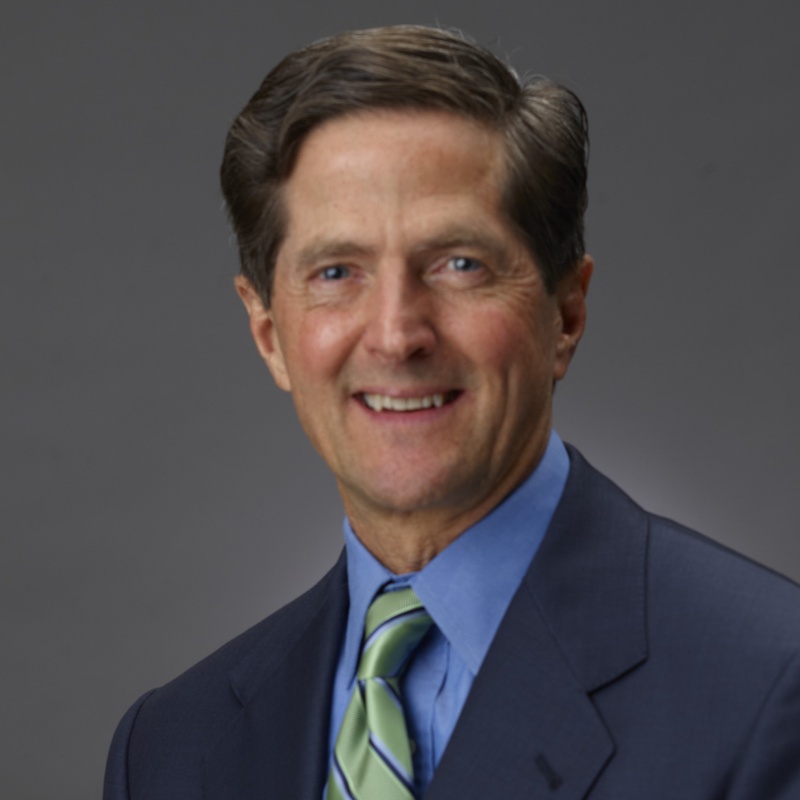
Thomas H. Yorke, CFP®
Over 30 years of institutional and retail investing experience across EF Hutton, Lehman Brothers, and Refco Securities. A CERTIFIED FINANCIAL PLANNER™ and lifelong Monmouth County resident.
Review Your 401(k) Rollover Options
If you want a clear, side-by-side look at what to do with your retirement savings, we would welcome a conversation. We will walk through every option and the tax consequences of each, then help you decide the path that fits your goals.
Frequently Asked Questions
What are the benefits of rolling a 401(k) into an IRA?
Rolling a former employer's 401(k) into an IRA can give you access to a wider range of investments, more control over your portfolio, and in some cases lower fees than an employer plan. Consolidating old accounts into one IRA can also make your retirement savings easier to manage and monitor. The right choice depends on your specific plan's fees, investment menu, and your tax situation.
Can I roll over my 401(k) while I am still employed?
Sometimes. Certain plans allow in-service distributions, which let you roll a portion of your 401(k) into an IRA without leaving your job. Eligibility depends on your plan's rules and often your age. We review your plan document to confirm whether an in-service rollover is available to you before starting the process.
What is the difference between a direct and an indirect rollover?
In a direct rollover, funds move trustee to trustee straight from your 401(k) to your IRA, with no taxes withheld and no 60-day deadline. In an indirect rollover, the money is paid to you first and you must redeposit the full amount into an eligible account within 60 days to avoid taxes and possible penalties. Employer plans also withhold 20% for federal taxes on an indirect distribution, which you must replace from other funds to roll the full balance over. For most people, a direct rollover is the simpler and safer route.
Can you roll a 401(k) into an IRA without penalty?
Yes. A properly executed rollover into an IRA is not a taxable event. A direct, trustee-to-trustee rollover is the simplest way to avoid penalties and unnecessary taxes. With an indirect rollover you must redeposit the funds within 60 days to stay penalty-free. Taking a distribution before age 59½ and not rolling it over may trigger a 10% additional federal tax on the taxable amount unless an exception applies, per IRS Topic No. 413.
What are my options for an old 401(k) when I change jobs?
You generally have four choices: leave the money in your former employer's plan, move it into your new employer's plan if allowed, roll it into an IRA, or cash it out. Cashing out can trigger taxes and an early-distribution penalty, so it is usually the least favorable option. We help you compare the fees, investment choices, and tax consequences of each path so you can decide with a full picture.
Where is Oceanic Capital located and who do you serve?
Our office is at 125 Half Mile Road, Suite 200, Red Bank, NJ 07701. We serve families and business owners throughout Monmouth County and Ocean County, including Middletown, Rumson, Holmdel, Colts Neck, and the surrounding Jersey Shore communities. Meetings are available in person or virtually. You can reach us at 732-933-2695.
Sources:
Internal Revenue Service, Topic No. 413, Rollovers From Retirement Plans. irs.gov/taxtopics/tc413 Internal Revenue Service, Rollovers of Retirement Plan and IRA Distributions. irs.gov/retirement-plans/rollovers-of-retirement-plan-and-ira-distributions Internal Revenue Service, Retirement Topics: Exceptions to Tax on Early Distributions. irs.gov/retirement-plans/retirement-topics-exceptions-to-tax-on-early-distributions
Take Charge of Your 401(k)
Keep up with your financial needs while avoiding common (and expensive) rollover mistakes. We put together this guide help you avoid these critical mistakes and potentially save you thousands in taxes and fees.