Retirement Planning for Individuals and Families
You spent a career saving for retirement in a 401(k), an IRA, and personal accounts. The harder question is how to turn that into income that lasts. As independent fee-based fiduciary CFP® professionals, we help individuals and families across Monmouth County build a retirement income plan they can rely on.
From Saving to Spending In Retirement With Confidence
For most of your working life, retirement planning meant one thing: save more. As retirement approaches, the questions change and get harder. When should you claim Social Security? Which accounts do you draw from first? How much can you spend without running out? Getting these wrong is costly, and unlike a savings shortfall, some of these decisions cannot be undone.
We help individuals answer them with a plan built around your actual life, not a rule of thumb. We map your income sources, your spending, your tax picture, and how long your money may need to last, then coordinate the moving parts so your retirement income is tax-efficient and durable. Because we are an independent fiduciary firm, our recommendations are made in your best interest.
Whether you are ten years out and want to know if you are on track, or already retired and want a second opinion on your withdrawal strategy, the goal is the same: clarity about whether your plan holds.
What We Help Individuals Plan For
Retirement Income Planning
A withdrawal strategy that turns your accounts into steady income, sequenced so more of what you saved reaches you.
Social Security Timing
Deciding when to claim. The Social Security Administration reduces benefits claimed before full retirement age and increases them for each year you delay to age 70.
Tax-Efficient Withdrawals
Coordinating draws across taxable, tax-deferred, and Roth accounts, alongside Roth conversions and required minimum distributions. See our tax planning.
401(k) and IRA Rollovers
Deciding whether and how to consolidate old workplace plans. See our 401(k) rollover guidance.
Investment Management
Portfolios aligned to your retirement timeline through our investment management approach, balancing growth and stability.
Healthcare and Longevity
Planning for Medicare decisions and a potentially long retirement, so a plan built at 65 still works decades later.
Why Work With Oceanic Capital
Retirement income decisions reward experience and cost real money when rushed. Our two managing directors bring more than 50 years of combined experience and serve as fiduciaries, aligned with you.
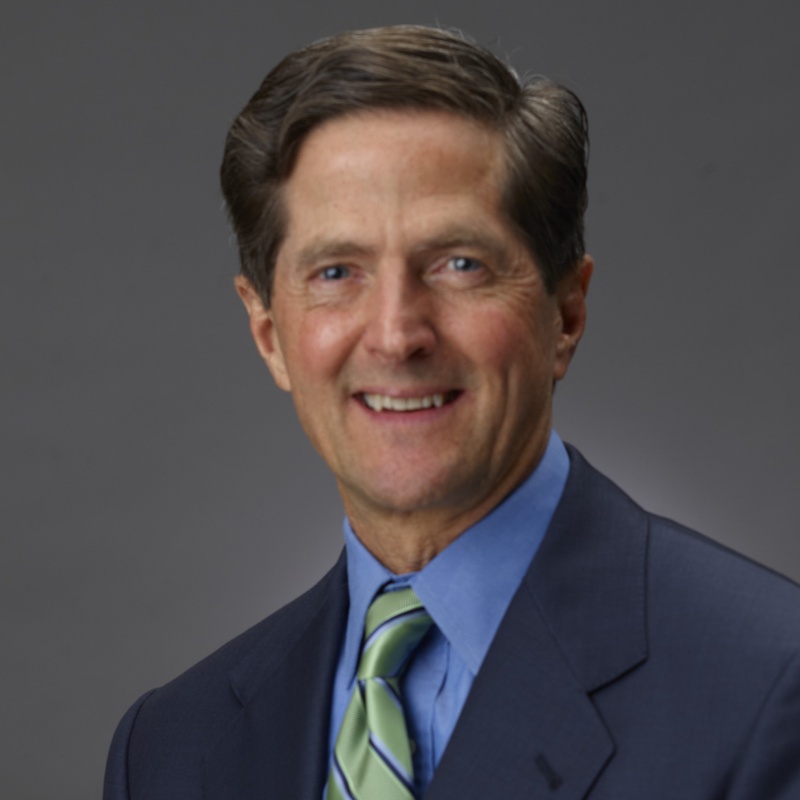
Thomas H. Yorke, CFP®
Managing Director
A CERTIFIED FINANCIAL PLANNER™ professional with more than 30 years of investing experience, Tom helps individuals structure portfolios and income strategies that carry through a long retirement.
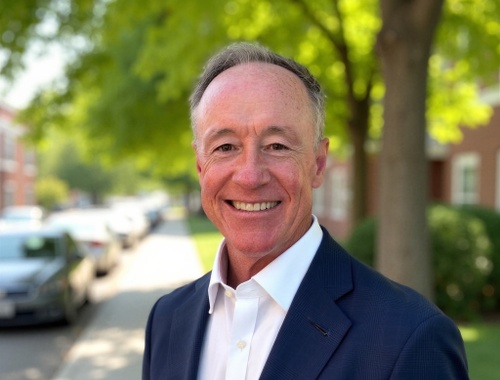
Douglas J. Lyons, CFP®, CFA®, CDFA®
Managing Director
A CFP®, CFA®, and CDFA® professional, Doug listens first, then builds a retirement income and tax strategy around each individual's goals and family situation.
Areas We Serve
We advise individuals and families from our Red Bank office and across Monmouth County, New Jersey.
See Whether Your Retirement Plan Meets Your Needs
Whether you are approaching retirement or already there, a fiduciary second look at your income and withdrawal strategy is worth the conversation.
Schedule an Individual Retirement ReviewFrequently Asked Questions
How do I know if I have saved enough to retire?
The answer is not a single number; it depends on your spending, your other income such as Social Security, your taxes, and how long your retirement may last. We model your real expenses against your income sources so you can see whether your plan holds under different market and longevity scenarios, rather than guessing from a generic multiple of salary.
When should I claim Social Security?
It depends on your health, your other income, and your overall plan. The Social Security Administration reduces benefits taken before your full retirement age and increases them for each year you wait, up to age 70. We model the timing alongside the rest of your income so the claiming decision fits your full picture rather than being made on its own.
Which accounts should I withdraw from first in retirement?
For many retirees, drawing thoughtfully across taxable, tax-deferred, and Roth accounts, rather than emptying one type first, reduces lifetime taxes and can extend how long the money lasts. The right sequence depends on your tax bracket, your required minimum distributions, and your goals, which is why we build it into your plan rather than applying a one-size rule.
Should I roll over my old 401(k)?
Sometimes consolidating old workplace plans into an IRA simplifies management and broadens your investment options, but not always; some plans have features worth keeping. We look at the specifics before recommending a move. Our 401(k) rollover page covers the trade-offs.
How do you charge for retirement planning?
Oceanic Capital is a fee-based advisory firm. We charge a transparent fee based on the assets we manage for you rather than commissions, which keeps our interests aligned with yours. The initial consultation is complimentary.