Tax Planning Strategies

The investments you hold, the accounts you draw from, and the year you take income all shape what you owe. As fee-based fiduciary CFP® professionals in Red Bank, we build proactive, year-round tax strategy into your wider financial plan, so you can keep more of what you earn and invest.

Fiduciary
Legally obligated to put your interests first
CFP®
Certified Financial Planner professionals
Red Bank, NJ
Local advisors rooted in Monmouth County
50+ Years
Combined advisory experience

What Tax Planning Strategies Involve

Tax planning is the process of arranging when you take income, which accounts you draw from, and how your investments are structured, so that your tax bill is managed on purpose rather than left to chance each April. For most households in Monmouth County, the gap between filing a return and planning around it can add up to real money kept over a lifetime.

Good tax strategy is forward looking, not a once-a-year event. It coordinates your portfolio, your retirement accounts, and your charitable and estate goals across many years, weighing choices such as Roth conversions, the order you spend down accounts in retirement, how gains and losses are realized, and how charitable giving is timed. Each of these decisions moves your taxable income, and the right mix depends on your bracket today and the bracket you expect later.

At Oceanic Capital Management, our CFP® professionals build tax awareness into every part of your plan, working alongside your accountant rather than replacing them. We are a fee-based fiduciary Registered Investment Advisory firm, which means our recommendations are made in your best interest. This page is one part of our wider investment management approach, and it connects to the retirement, estate, and charitable decisions that share the same tax strategy.

Why the Same Dollar Can Be Taxed So Differently

How much tax you pay is not only about how much you make; it is about how and when that income reaches you. The same dollar of growth can face very different federal rates depending on whether it arrives as ordinary income or as a long-term capital gain. These are the current federal rate ceilings, and the distance between them is the opportunity that planning is built to capture.

0% LONG-TERM GAIN
Lowest bracket
Long-term capital gains

Long-term gains and qualified dividends can be taxed at 0% for taxpayers within the lowest income band. Realizing gains in a low-income year is one way planning puts this rate to work.

20% LONG-TERM GAIN
Highest bracket
Long-term capital gains

Even at the top, a long-term capital gain is taxed at no more than 20%. Holding an investment longer than a year is what moves growth out of ordinary rates and into this range.

37% ORDINARY INCOME
Highest bracket
Ordinary income

Wages, interest, and short-term gains are taxed as ordinary income, topping out at 37%. That is nearly double the top long-term rate, which is why the type and timing of income matters.

17 pts

At the top of the schedule, the spread between ordinary income and a long-term capital gain is 17 percentage points. Decisions about holding periods, account location, and the timing of income are how a plan works to keep more of your return on the lower side of that gap.

Rates are the current federal figures from the Internal Revenue Service and exclude the 3.8% net investment income tax, state income tax, and your personal circumstances. They are shown for illustration and are not individualized tax advice.

Our Tax Planning Services

We do not file your return. We plan around it, all year long, so the moves that lower your lifetime tax bill happen before the deadline rather than after it. Here is how we help clients in Red Bank and across Monmouth County keep more of what they build, working alongside your accountant.

Tax-efficient investing

We locate assets across taxable, tax-deferred, and Roth accounts so growth is held where it is taxed least, and we manage how and when gains and losses are realized across your portfolio.

Roth conversion analysis

Converting pre-tax savings to a Roth can lower lifetime taxes when done in the right years. We model conversions against your current and expected brackets so you fill lower brackets without tipping into higher ones.

Retirement withdrawal sequencing

The order you draw from accounts in retirement shapes your tax bill for decades. We build a withdrawal strategy that coordinates Social Security, required minimum distributions, and your taxable accounts.

Charitable giving strategy

Giving can be a tax strategy as well as a value. We help with donating appreciated securities, bunching gifts, donor-advised funds, and qualified charitable distributions so your generosity is tax-smart.

Estate and legacy tax planning

We coordinate with your estate attorney so wealth passes to the next generation with the tax impact considered, weighing gifting, step-up in basis, and the federal and New Jersey rules that apply to your situation.

Fiduciary tax second opinion

Already have a plan or a conversion in mind? We offer a no-pressure fiduciary review to confirm your strategy holds up, or to flag opportunities you may be leaving on the table before year-end.

Why Investors Chose Us

Good tax planning comes down to the detials. Our value is in experience, transparency, and a fiduciary standard of care that puts your interests first, with recommendations driven by your plan rather than by products.

We are an independent Registered Investment Advisory firm rooted in Red Bank, New Jersey, so you get a direct relationship with the advisors building your tax strategy and face-to-face meetings when you want them.

  • Fiduciary Standard Of Care

    As a fee-based fiduciary RIA, we are obligated to act in your best interest, with planning recommendations driven by your goals, not product sales.

  • Decades Of Combined Experience

    Our two managing directors each bring more than 30 years of guiding clients through changing tax law, market cycles, and major life transitions.

  • CFP® And CFA® Credentials

    Both directors are CERTIFIED FINANCIAL PLANNER™ professionals, bringing rigorous training in the tax, retirement, and investment decisions that shape your return.

  • Coordinated With Your Accountant

    We work alongside your CPA or tax preparer, not in place of them, so your planning and your filing stay aligned throughout the year.
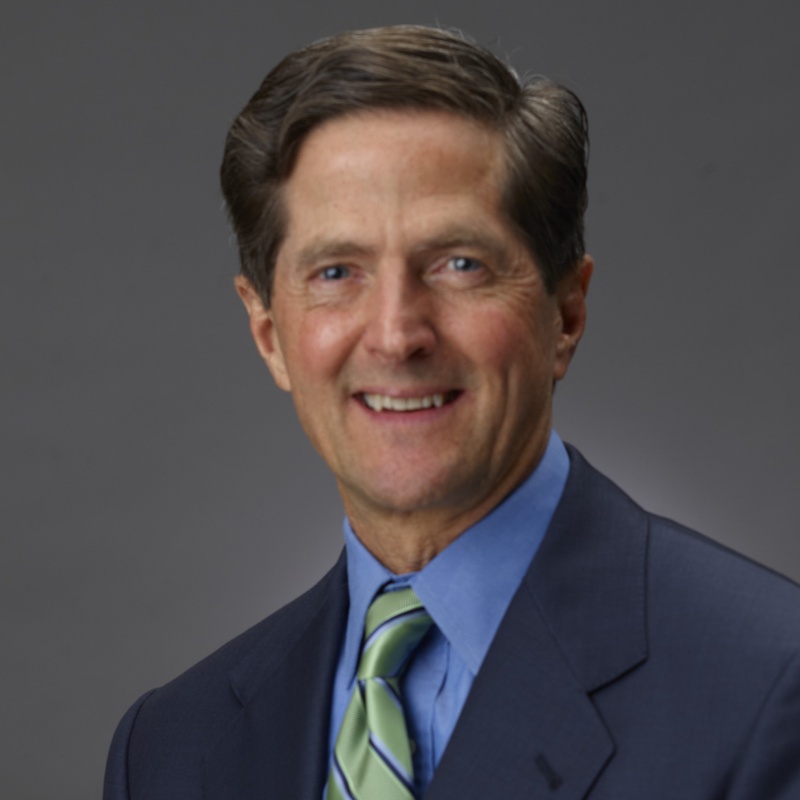
Thomas H. Yorke, CFP

Thomas H. Yorke, CFP®

Managing Director

Over 30 years of institutional and retail investing experience across EF Hutton, Lehman Brothers, and Refco Securities. A CERTIFIED FINANCIAL PLANNER™ and lifelong Monmouth County resident.
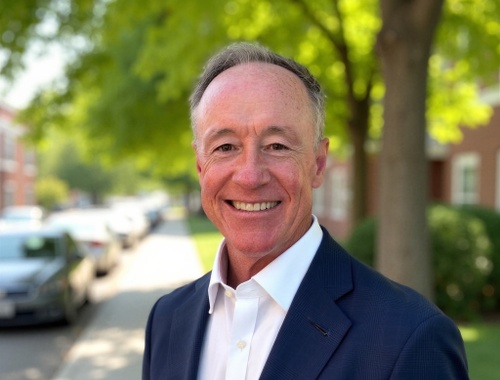
Douglas J Lyons, CFP, CFA, CDFA

Douglas J Lyons, CFP®, CFA®, CDFA®

Managing Director

More than 30 years advising clients, formerly Executive Director of Private Wealth Consultants at UBS and part of Merrill Lynch's planning team. Holds the CFA®, CFP®, and CDFA® designations.

Tax Planning for Monmouth County and Beyond

Our office sits on Half Mile Road in Red Bank, and we work with individuals, families, and business owners across Monmouth and Ocean County. We meet in person when you want to and virtually when that is easier, so where you live is never a barrier to a well-planned tax strategy.

Oceanic Capital Management

125 Half Mile Road, Suite 200
Red Bank, NJ 07701
732-933-2695
Communities we serve
  • Red Bank
  • Middletown
  • Rumson
  • Fair Haven
  • Little Silver
  • Holmdel
  • Colts Neck
  • Monmouth County
  • Ocean County

Build a Smarter Tax Strategy With Confidence

The right tax moves happen before the deadline, not after it. Sit down with a fiduciary CFP® professional in Red Bank and build a proactive, year-round tax strategy into your wider financial plan.

Complimentary tax planning review in Red Bank and Monmouth County

Tax Planning FAQs

Straight answers to the questions people in Red Bank and Monmouth County ask us most about tax planning. If your question is not here, we are glad to answer it directly.

Tax preparation is backward looking: it reports what already happened on last year's return. Tax planning is forward looking: it shapes decisions during the year, such as Roth conversions, the timing of income and gains, and charitable giving, so your future tax bill is lower by design. We handle the planning and coordinate with your accountant, who handles the filing, so the two work together.

Year round, not just in April. Many of the most valuable moves, such as Roth conversions, realizing gains or losses, and charitable gifts, must be completed by December 31 to count for that tax year, and some require months of lead time. We review your situation through the year and act while there is still time to make a difference, rather than reacting after the year has closed.

Yes. A fiduciary financial advisor helps lower your lifetime tax bill by coordinating how your investments are structured, which accounts you draw from, and when you take income. At Oceanic Capital Management, our CFP professionals build tax awareness into your full plan, and because we are a fee-based fiduciary, our recommendations are based on what is best for you rather than on product sales.

A Roth conversion moves money from a pre-tax account, such as a traditional IRA, into a Roth account, so you pay tax on it now in exchange for tax-free growth and withdrawals later. It can lower your lifetime taxes when it is done in years where your bracket is lower than you expect it to be in the future. Because a conversion adds to your taxable income, the amount and timing matter, so we model it against your brackets before recommending one.

No. We are financial advisors, not tax preparers, so we do not file returns or give formal tax advice. We work alongside your accountant or CPA, sharing the planning behind your investment and retirement decisions so your filing and your strategy stay aligned. If you do not have a tax preparer, we are glad to coordinate with one you choose.

The order you draw from your accounts in retirement can change your tax bill for decades. We build a withdrawal strategy that sequences your taxable, tax-deferred, and Roth accounts and coordinates them with Social Security and required minimum distributions, so more of your retirement income stays with you. This is the same tax-aware approach we bring to the rest of your plan.

Your initial consultation is complimentary. Oceanic Capital Management is a fee-based advisory firm, and tax planning is provided as part of our broader investment and wealth management relationship. We will explain how we are compensated clearly and up front, so you can decide whether working together is the right fit before any commitment.