Retirement Planning for Business Owners
For most business owners, the company is the retirement plan, and its value stays locked up until you sell, transition, or wind it down. As independent fee-based fiduciary CFP® professionals, we help owners across Monmouth County turn years of building a business into personal retirement income.
The Retirement Challenges Unique to Business Owners
When you own a business, your net worth and your retirement are often the same thing, concentrated in one illiquid asset you cannot spend a slice of when you need income. That concentration creates risk an employee never faces, and it makes the timing and structure of your exit one of the most consequential financial decisions of your life.
It also creates opportunity. Owners have access to retirement plan structures, tax strategies, and succession options that most individuals do not. Used well, they let you shelter more income, reduce the tax drag on a sale, and build personal wealth outside the business so your retirement does not depend entirely on one buyer showing up at the right price.
We coordinate the business side and the personal side of the plan together, working alongside your CPA and attorney so decisions about the company and decisions about your retirement reinforce each other rather than pull in different directions.
How We Help Business Owners Plan for Retirement
Choosing the Right Retirement Plan
Comparing SEP-IRA, SIMPLE IRA, 401(k), and defined benefit plan structures so you shelter income efficiently based on your business size, cash flow, and employee count.
Business Exit and Succession
Planning the transition, whether a third-party sale, a family handoff, or a buyout, so the proceeds support your retirement income rather than a large one-time tax bill.
Concentration Risk
Building personal wealth outside the business over time, so your retirement is not dependent on a single liquidity event.
Tax-Efficient Sale Planning
Coordinating with your CPA on the tax treatment of a sale and how proceeds integrate with your broader tax plan.
Turning Proceeds Into Income
Investing sale proceeds for durable retirement income through our investment management approach.
Key-Person and Legacy
Coordinating estate and beneficiary planning so the wealth you built transfers the way you intend.
Why Work With Oceanic Capital
Owner decisions are hard to undo, so experience matters. Our two managing directors bring more than 50 years of combined experience and act as fiduciaries, on your side of the table.
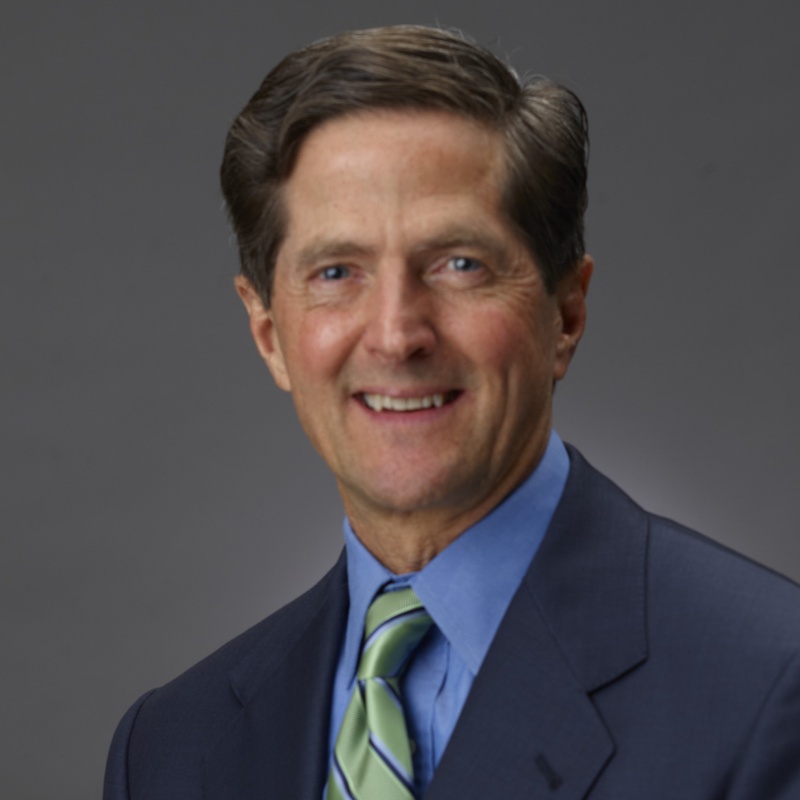
Thomas H. Yorke, CFP®
Managing Director
With more than 30 years of institutional and retail investing experience, Tom helps owners diversify wealth beyond the business and structure portfolios that turn a liquidity event into lasting retirement income.
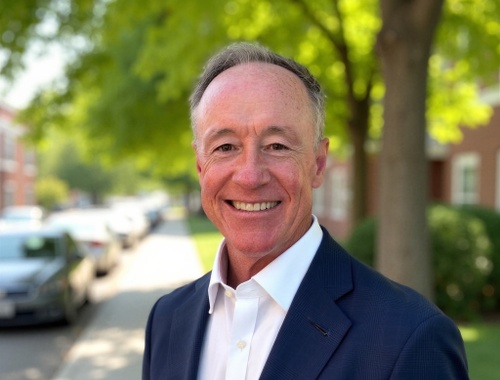
Douglas J. Lyons, CFP®, CFA®, CDFA®
Managing Director
A CFP®, CFA®, and CDFA® professional, Doug partners with owners and their CPAs and attorneys to align retirement plan structure, succession, and personal strategy around each owner's goals.
Areas We Serve
We advise business owners from our Red Bank office and across Monmouth County, New Jersey.
Plan the Retirement Your Business Has Earned
If your company is your retirement plan, the exit and the income strategy deserve as much attention as building the business did. Request a complimentary review with a fiduciary CFP® professional.
Schedule a Business Owner Retirement ReviewFrequently Asked Questions
What is the best retirement plan for a business owner?
It depends on your income, your cash flow, and whether you have employees. A SEP-IRA is simple and allows large contributions for owners with few or no employees. A solo 401(k) can allow even higher contributions for an owner-only business. A defined benefit plan can shelter substantially more for older, high-income owners. We compare the structures against your specific situation rather than defaulting to one.
How does selling my business fit into my retirement plan?
A sale is often the single largest financial event an owner will face, and its timing and structure affect how much you keep. We plan the exit alongside your retirement income needs and coordinate with your CPA on tax treatment, so the proceeds are positioned to fund your retirement rather than trigger an avoidable tax bill.
I have most of my wealth in my business. Is that a problem?
It is a common situation and a real risk, because your retirement depends on one illiquid asset and one eventual buyer. Over time we help owners build wealth outside the business so retirement income does not hinge entirely on a single liquidity event going perfectly.
When should a business owner start retirement planning?
Earlier is better, ideally several years before a planned exit, because the most valuable strategies such as plan selection, wealth diversification, and tax-efficient exit structuring need lead time to work. If a sale is already close, planning still helps you keep more of the proceeds.
How do you charge, and do you work with my CPA and attorney?
Oceanic Capital is a fee-based advisory firm; we charge a transparent fee based on the assets we manage rather than commissions, which keeps our interests aligned with yours. We regularly work alongside owners' CPAs and attorneys so the tax, legal, and investment pieces fit together. The initial consultation is complimentary.