Healthcare and Longevity Planning
Planning for Medicare decisions, rising healthcare costs, and the real possibility of a long retirement, so a plan built at 65 still holds at 90.
Request a Longevity Planning ConsultationPlanning for a Longer, Healthier Retirement
Most retirement plans quietly assume a healthy, predictable life of a certain length. Real retirements are neither. People are living longer than the generation before them, and the two largest wildcards in a long retirement, healthcare costs and how many years the plan has to cover, are exactly the ones most plans leave to chance.
Healthcare and longevity planning brings those wildcards into the plan on purpose. It means making Medicare choices with eyes open, setting money aside for out-of-pocket medical and dental costs Medicare does not cover, weighing whether long-term care protection belongs in your plan, and stress-testing your income against a retirement that could stretch three decades. At Oceanic Capital Management, an independent Registered Investment Advisory firm in Red Bank, we build these considerations into your plan, and our advisory recommendations are made in your best interest.
Why Planning For Your Healthcare and
Longevity Makes A Difference
Two forces quietly shape whether a retirement plan holds up: how long it has to last, and how much of it healthcare consumes. Both are larger than most people expect.
Retirements Are Getting Longer
A 65-year-old today can expect to live roughly two more decades on average, and a meaningful share will reach their 90s. A plan that only comfortably covers 20 years leaves real risk on the table if you are one of the many who live longer.
Source: Social Security Administration actuarial life tables, ssa.gov.Medicare Does Not Cover Everything
Medicare leaves premiums, deductibles, and coinsurance to you, and generally does not cover most long-term care, routine dental, or vision. Those gaps are real spending your plan needs to account for, not rounding errors.
Source: Medicare.gov, what Part A and Part B do not cover, medicare.gov.Long-Term Care Is a Common Need
The U.S. Department of Health and Human Services estimates that most people turning 65 will need some form of long-term care in their lives. Deciding in advance how to fund that possibility keeps it from derailing the rest of your plan.
Source: U.S. Dept. of Health & Human Services, acl.gov/ltc.How We Help
Health and longevity planning is a set of connected decisions, most of which are easier and less expensive to make before they become urgent. We work through each one with you.
Budgeting for Healthcare Costs
We build realistic healthcare spending into your retirement income plan, covering premiums, out-of-pocket costs, and the dental and vision expenses Medicare leaves to you, so those bills do not surprise your plan.
Navigating Medicare Decisions
We help you understand the timing and tradeoffs of Medicare enrollment and supplemental coverage so your choices fit your health and budget. For specific enrollment and coverage rules we point you to Medicare and licensed specialists.
Long-Term Care Strategy
We help you weigh how to prepare for a potential long-term care need, whether through dedicated savings, insurance, or a blend, and coordinate that choice with the rest of your plan.
Stress-Testing for a Long Retirement
We model your income against a retirement that lasts into your 90s, so we can see early whether your plan holds and adjust while there is still time to act. This ties directly to your retirement income plan.
Coordinating With Your Estate Plan
Health decisions and wishes belong alongside your wealth transfer plan. We coordinate with your estate planning so beneficiary and care intentions stay aligned.
Tax-Aware Funding of Health Costs
We consider how you draw from taxable, tax-deferred, and Roth accounts to cover medical costs, coordinating with your broader tax planning so healthcare spending stays efficient.
Why Work With Oceanic Capital
Planning for health costs and a long life touches every other part of your plan, so it helps to have advisors who see the whole picture. Our value comes from experience, transparency, and a standard of care that keeps your interests first.
- ✓
Fiduciary Standard of Care
As an independent Registered Investment Advisory firm, our advisory recommendations are made in your best interest, not driven by product sales.
- ✓
Fee-Based, Transparent Advice
We are compensated through a clear fee based on the assets we manage for you rather than commissions, so our guidance stays aligned with your plan.
- ✓
Coordinated, Whole-Picture Planning
We connect healthcare and longevity decisions with your income, tax, and estate plans so no part works against another.
- ✓
Rooted in Red Bank, NJ
We live and work where our clients do, and we meet with you face to face at our Red Bank office.
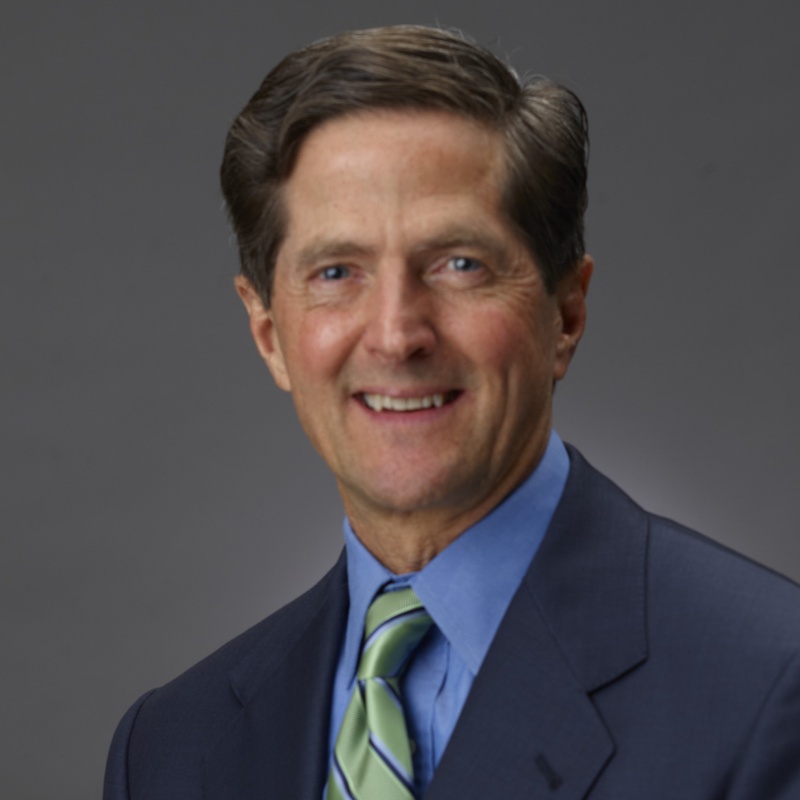
Thomas H. Yorke, CFP®
A CERTIFIED FINANCIAL PLANNER™ professional with more than 30 years of institutional and retail investing experience, bringing a holistic approach to protecting clients' wealth through a long retirement.
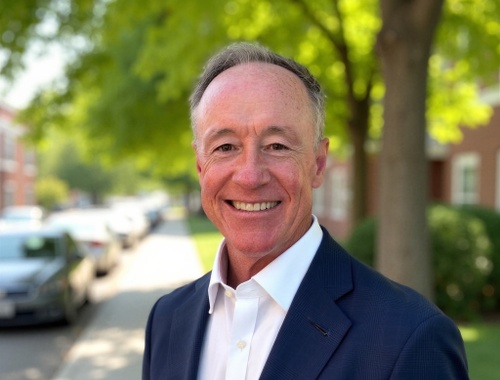
Douglas J. Lyons, CFP®, CFA®, CDFA®
A CERTIFIED FINANCIAL PLANNER™ professional and Chartered Financial Analyst® with more than 30 years of experience advising families and executives on planning that lasts across Monmouth County.
Areas We Serve
From our office in Red Bank, we help individuals, couples, and business owners plan for healthcare costs and a long retirement across Monmouth County and throughout New Jersey.
Serving clients throughout New Jersey. Advisory services are offered where the firm is registered or exempt from registration.
Plan for the Long Haul With Confidence
If you want a plan that accounts for healthcare costs and a long, healthy retirement, we would welcome a conversation. Request a consultation and we will help you budget for medical costs, weigh long-term care, and stress-test your plan for the years ahead.
Request a Longevity Planning ConsultationFrequently Asked Questions
What is healthcare and longevity planning?
It is the part of retirement planning that accounts for medical costs and the length of your retirement. It means budgeting for premiums and out-of-pocket healthcare, making informed Medicare decisions, weighing long-term care, and testing whether your income holds up if you live into your 90s.
How much should I budget for healthcare in retirement?
There is no one figure that fits everyone, because it depends on your health, coverage choices, and how long you live. Medicare covers a great deal but leaves premiums, deductibles, coinsurance, and most dental, vision, and long-term care to you. We build a realistic healthcare line into your income plan and revisit it as costs and your needs change.
Does Oceanic Capital sell Medicare plans or long-term care insurance?
No. As an independent Registered Investment Advisory firm, we help you understand how these decisions fit your overall plan and coordinate with licensed insurance and Medicare specialists for the products themselves. Our role is planning and advice made in your best interest, not selling policies.
How do you plan for the possibility of a very long retirement?
We model your income against a retirement that could last into your 90s rather than a shorter average, so we can see early whether your plan holds. If a gap appears, we can adjust spending, investments, or the timing of income while there is still time to act.
How does Oceanic Capital charge for this planning?
As an independent Registered Investment Advisory firm, we are fee-based and compensated through a transparent fee based on the assets we manage for you, rather than commissions. That keeps our advice aligned with your plan. We are glad to walk through how it works during an initial consultation.