Retirement Planning

Retirement Income Strategy

Building a paycheck from your savings takes more than a withdrawal rate. It takes a plan that sequences income across your accounts, manages taxes year by year, and holds steady through a long retirement.

Schedule a Retirement Income Consultation
  • Fiduciary Independent RIA, obligated to put your interests first
  • CFP® CERTIFIED FINANCIAL PLANNER™ professionals
  • Red Bank, NJ Advisors rooted in Monmouth County
  • 50+ Years Combined advisory experience

Turning a Lifetime of Saving Into Reliable Income

Saving for retirement and spending in retirement are two very different problems. For decades the goal was to accumulate, so you added to your accounts and let them grow. The moment you stop working, that question flips: now the balances you built have to produce a paycheck that covers your life for as long as you live, in a way that keeps your tax bill low and your plan steady through good markets and bad ones.

A retirement income strategy answers that question deliberately rather than by default. Instead of pulling from whatever account is easiest, it decides which dollars to spend first, how to cover the gap between your expenses and guaranteed sources like Social Security, and how to keep withdrawals sustainable if retirement lasts thirty years or more. At Oceanic Capital Management, an independent Registered Investment Advisory firm in Red Bank, we build that plan around your actual expenses, accounts, and goals, and our advisory recommendations are made in your best interest.

Why an Income Strategy Matters

Without a plan, the order in which you spend accounts is left to chance, and that chance can cost you years of income. Three risks make the difference between a plan that holds and one that runs short.

Longevity

A 65-year-old today can expect to live roughly two more decades on average, and many will live well beyond that. Planning for a retirement that could stretch past 90 means your income cannot be built to last only a handful of years.

Source: Social Security Administration actuarial life tables, ssa.gov.

Sequence of Returns

Withdrawing from a portfolio during an early market downturn does lasting damage, because you are selling more shares to fund the same income and leaving less to recover. The order of good and bad years, not just the average, shapes how long your money lasts.

Taxes on Every Dollar

Taxable, tax-deferred, and Roth accounts are each taxed differently when you draw from them. Required minimum distributions from tax-deferred accounts generally begin at age 73, so the sequence you withdraw in has a direct effect on your lifetime tax bill.

Source: IRS required minimum distribution rules, irs.gov.

How We Build Your Retirement Income

Your income plan is assembled from a few connected decisions. We work through each one with you, then keep them coordinated as markets, tax law, and your life change.

Mapping Income to Expenses

We start with what your retirement truly costs, separating essential expenses from the discretionary spending that makes retirement enjoyable, then match reliable income sources to the essentials first.

Withdrawal Sequencing

We decide which accounts to draw from and in what order across taxable, tax-deferred, and Roth balances, so more of what you saved reaches you rather than the IRS. This works hand in hand with your tax planning.

Coordinating Guaranteed Income

We fit your portfolio withdrawals around Social Security and any pension so the pieces work together. When to claim benefits is its own decision, covered on our Social Security timing page.

A Portfolio Built for Withdrawals

We manage the underlying investments for a retirement timeline, balancing growth for later years against the stability the income you spend today depends on. See our investment management approach.

A Cash Reserve for Down Markets

We keep a defined reserve of near-term spending set aside so a market drop does not force you to sell investments at the wrong time to fund your next few withdrawals.

Annual Review and Adjustment

Retirement rarely runs in a straight line. We revisit your spending, portfolio, and tax situation each year and adjust the plan so it keeps pace with your life.

Why Work With Oceanic Capital

Your retirement income runs through the accounts you spent a lifetime building, so the advisor guiding those withdrawals matters. Our value comes from experience, transparency, and a standard of care that keeps your interests first.

  • Fiduciary Standard of Care

    As an independent Registered Investment Advisory firm, our advisory recommendations are made in your best interest, not driven by product sales.

  • Fee-Based, Transparent Advice

    We are compensated through a clear fee based on the assets we manage for you rather than commissions, so our guidance stays aligned with your plan.

  • Decades on Wall Street and Main Street

    Our advisors bring institutional investing careers to the personal work of building income for families in Monmouth County.

  • Rooted in Red Bank, NJ

    We live and work where our clients do, and we meet with you face to face at our Red Bank office.
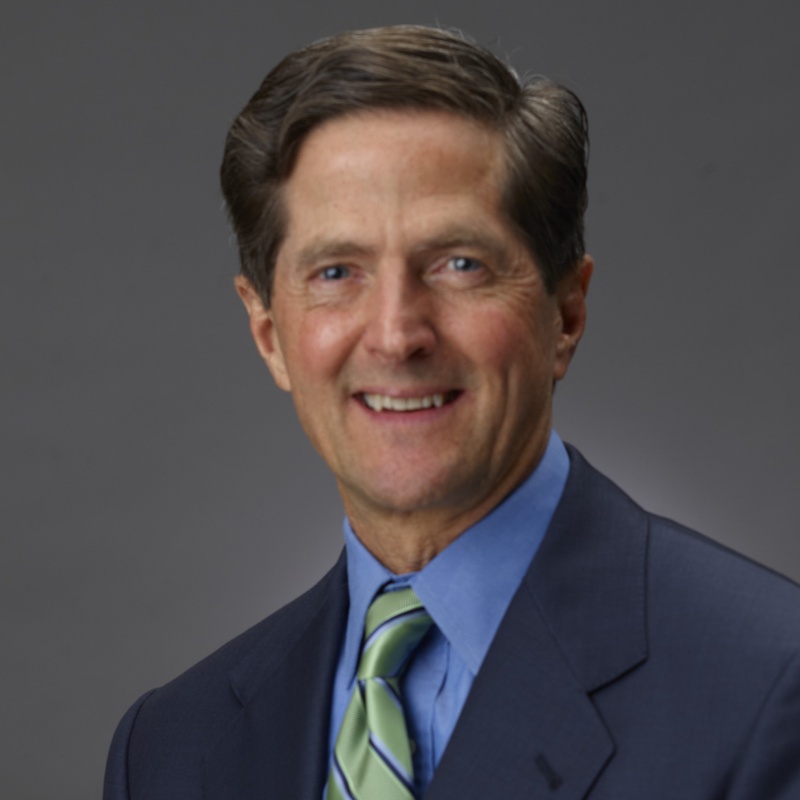
Thomas H. Yorke, CFP

Thomas H. Yorke, CFP®

Managing Director

A CERTIFIED FINANCIAL PLANNER™ professional with more than 30 years of institutional and retail investing experience, including fixed income and portfolio work at EF Hutton, Lehman Brothers, and Refco Securities.
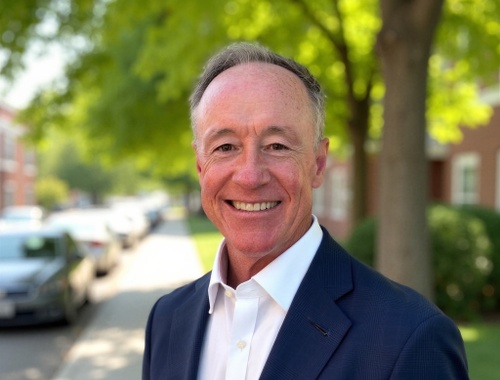
Douglas J. Lyons, CFP, CFA, CDFA

Douglas J. Lyons, CFP®, CFA®, CDFA®

Managing Director

A CERTIFIED FINANCIAL PLANNER™ professional and Chartered Financial Analyst® with more than 30 years of experience, including private wealth roles at UBS and Merrill Lynch, advising families and executives across Monmouth County.

Areas We Serve

From our office in Red Bank, we build retirement income plans for individuals, couples, and business owners across Monmouth County and throughout New Jersey.

Map of the Red Bank and Monmouth County, NJ area Oceanic Capital Management serves
Red Bank
Middletown
Colts Neck
Rumson
Little Silver
Fair Haven
Holmdel
Shrewsbury

Monmouth County

Serving clients throughout New Jersey. Advisory services are offered where the firm is registered or exempt from registration.

Plan for the Long Haul With Confidence

If you want a plan that accounts for healthcare costs and a long, healthy retirement, we would welcome a conversation. Request a consultation and we will help you budget for medical costs, weigh long-term care, and stress-test your plan for the years ahead.

Request a Longevity Planning Consultation

Frequently Asked Questions

What is healthcare and longevity planning?

It is the part of retirement planning that accounts for medical costs and the length of your retirement. It means budgeting for premiums and out-of-pocket healthcare, making informed Medicare decisions, weighing long-term care, and testing whether your income holds up if you live into your 90s.

How much should I budget for healthcare in retirement?

There is no one figure that fits everyone, because it depends on your health, coverage choices, and how long you live. Medicare covers a great deal but leaves premiums, deductibles, coinsurance, and most dental, vision, and long-term care to you. We build a realistic healthcare line into your income plan and revisit it as costs and your needs change.

Does Oceanic Capital sell Medicare plans or long-term care insurance?

No. As an independent Registered Investment Advisory firm, we help you understand how these decisions fit your overall plan and coordinate with licensed insurance and Medicare specialists for the products themselves. Our role is planning and advice made in your best interest, not selling policies.

How do you plan for the possibility of a very long retirement?

We model your income against a retirement that could last into your 90s rather than a shorter average, so we can see early whether your plan holds. If a gap appears, we can adjust spending, investments, or the timing of income while there is still time to act.

How does Oceanic Capital charge for this planning?

As an independent Registered Investment Advisory firm, we are fee-based and compensated through a transparent fee based on the assets we manage for you, rather than commissions. That keeps our advice aligned with your plan. We are glad to walk through how it works during an initial consultation.